Trust investment management · Pennsylvania
Trust investment management for Pennsylvania trustees.
Serving as trustee comes with a legal duty to invest prudently for every beneficiary. Reese Legacy Capital manages trust portfolios for individual trustees, family members, and the attorneys and CPAs who advise them, with one fiduciary adviser accountable for every decision.
Every trust begins here
Investment policy statement
-
Trust purposes and terms
-
Current and remainder beneficiaries
-
Distribution needs
-
Risk and return objectives
-
Diversification and inception assets
-
Monitoring and reporting to the trustee
-
Prudent investor processPortfolios judged as a whole against the trust’s purposes and terms.
-
A written recordAn investment policy statement and the reasoning behind each decision.
-
You remain trusteeWe manage the investments for the trustee you choose. We don’t serve as trustee.
-
Schwab custodyAssets stay in the trust’s own name, with statements sent to the trustee.
Why trusts are different
A trustee isn’t investing for themselves.
They’re balancing the interests of current income beneficiaries against future remainder beneficiaries, under a legal standard that governs how prudently that has to be done.
A trust portfolio needs things an individual account usually doesn’t: total-return investing that treats beneficiaries fairly, a written record of the reasoning behind each decision, and a manager who understands that the trustee can be held personally accountable for how the portfolio is run.
Every trust portfolio is built around the trust document and the beneficiaries it serves.
Pennsylvania law, in plain English
Six Pennsylvania rules that shape a trust portfolio
Pennsylvania sets its own rules for how trust assets are invested, in Title 20 of the state’s consolidated statutes. They differ from the model laws in ways that matter to a trustee here.
The prudent investor rule is the keystone. It judges the portfolio as a whole, against the trust’s purposes and terms, rather than second-guessing each holding after the fact.
Prudent investor rule
20 Pa.C.S. § 7203
Invest as a prudent investor would, considering the trust’s purposes, terms and circumstances, with an overall strategy suited to the trust.
Every portfolio starts from the trust document and a written investment policy, and is judged as a whole.
Reasonable diversification
§ 7204
Diversify reasonably, unless there’s a sound reason, tied to the beneficiaries’ interests, not to.
Concentrated positions get a written plan: reduce them over time, or document why holding serves the beneficiaries.
Inception assets
§ 7205
Addresses when a trustee may keep assets the trust started with, such as a family company’s stock.
We review what the trust was funded with, and any instructions about it, before proposing changes.
Delegation
§ 7206
A trustee may delegate investment management, but must choose the manager carefully, set the scope and monitor the work.
We work under a written agreement that defines our scope, and report so the trustee can monitor us.
Unitrust conversion
§ 8105
Many trusts can switch from paying “income” to paying a fixed percentage of trust value, 4% by default.
Where counsel recommends it, a unitrust lets the portfolio invest for total return without shortchanging either set of beneficiaries.
Directed trusts
§ 7780.11 and following
Since 2024, a trust document can name someone other than the trustee to direct the investments.
We coordinate with the trustee and counsel on how a directed structure shapes the investment role.
A general summary for Pennsylvania trustees, not legal advice. Your trust document and trust counsel govern your duties. Our role is investing the trust well within them.
Watch: about 9 minutes
New trustee? Your five investment duties.
A plain-English walk through what Pennsylvania expects of a trustee, from reading the trust document to deciding when to bring in an investment manager. Educational only, not legal or tax advice.
How we work with your trust
Who does what
The trustee stays in place and hands day-to-day investment management to Reese Legacy Capital under a written agreement. Assets stay in the trust’s own name at Charles Schwab, which sends statements to the trustee directly.
We keep everyone informed, so tax, distribution and investment decisions line up.
Oversees
The trustee
Holds the fiduciary role, chooses the investment manager, sets the scope, and monitors the work. Makes the final call on distributions.
Invests
Reese Legacy Capital
Manages the portfolio with discretionary authority under a written agreement, documents each decision, and reports so the trustee can monitor.
Advises
Trust attorney
Advises the trustee on legal duties, the trust’s terms, and distributions.
Files
CPA
Prepares the trust’s fiduciary tax returns and advises on tax timing.
Holds the assets
Charles Schwab
Qualified custodian. Assets are held in the trust’s own name, and statements go to the trustee directly. Reese Legacy Capital never holds the money.
Why this practice exists
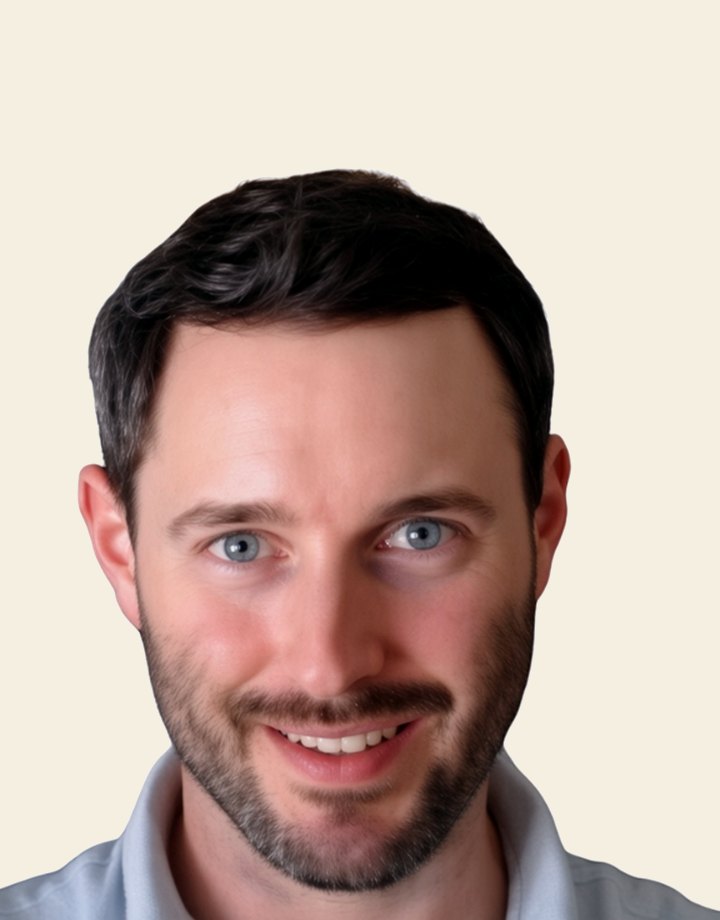
A trust I still manage myself.
I manage my own family’s trust today. It traces back to my great-grandfather, H.B. Reese, whose success with the peanut butter cup has lasted to this generation.
I founded Reese Legacy Capital to bring that same long-horizon care to other families and their trustees.
I know what it’s like to sit on the trustee’s side of the table: weighing what one beneficiary needs this year against what another will need in twenty, and wanting a clear written reason behind every move. That’s the standard every trust portfolio here is held to.
Who this is for
Who I work with
Individual and family trustees
Family members serving as trustee who want a manager that understands the legal weight of the role, including families moving on from a bank trust department.
Successor and co-trustees
Trustees stepping into an existing trust who need a clear, documented approach from day one.
Estate attorneys and CPAs
Professionals advising trustees who need a portfolio manager they can confidently bring into a client’s trust.
How we begin
How a trust account gets started
Review the trust document
Understanding the terms, the beneficiaries, and any specific investment provisions before proposing anything.
Meet with counsel, if involved
A short coordination call with the trust’s attorney or CPA when helpful, so everyone starts aligned.
Propose an investment approach
A written proposal and investment policy statement covering income needs, risk and fairness between beneficiaries.
Manage and report
Ongoing, discretionary management under the signed agreement, with regular, trust-aware reporting and documentation.
Fees
Fees
An annual percentage of the trust assets we manage, billed quarterly in arrears. Each rate applies only to the dollars in its tier. No commissions, product sales, or referral fees.
The minimum account size is $250,000, which may be reduced or waived on a case-by-case basis. Fees are negotiable. The signed advisory agreement controls.
Where we work
Serving trustees across south-central Pennsylvania.
- East Petersburg
- Lancaster
- Lititz
- Manheim Township
- Hershey
- Harrisburg
- York
- Reading
Meet in our East Petersburg office or by video. Trustees elsewhere in Pennsylvania are welcome.
Common questions
Questions trustees ask
Can I hire someone to manage the trust’s investments?
In most cases, yes. Pennsylvania’s prudent investor rule lets a trustee delegate investment management (20 Pa.C.S. § 7206), but the trustee keeps a duty to choose the manager carefully, define the scope and monitor the work. Your trust document and counsel have the final word. Read the full guide
Do you work directly with the trust’s attorney or CPA?
Yes, whenever the trustee wants that coordination. Many of the best trust relationships work as a team: attorney, CPA and portfolio manager, each doing their part.
How do you balance income and remainder beneficiaries?
Through total-return investing rather than favoring current income at the expense of growth, or the reverse. The balance depends on the trust’s terms and the beneficiaries’ actual circumstances, which we review closely before proposing an approach. In some trusts, a unitrust conversion makes that balance simpler.
How is this different from a bank trust department?
You work directly with the person making the investment decisions, and the portfolio is built for your trust. Reese Legacy Capital doesn’t serve as trustee. We manage the investments for the trustee you choose.
What does trust investment management cost?
Fee-only: an annual fee from 1.00% down to 0.60% of the assets we manage, blended by tier and billed quarterly in arrears. We’re paid by our clients, never by commissions. See the full fee schedule.
Is this legal advice about my duties as trustee?
No. We work closely alongside the trust’s attorney, but questions about your specific legal duties as trustee should always go to trust counsel. Our role is the investment management of the account.
What size trust accounts do you work with?
The minimum account size is $250,000, which may be reduced or waived on a case-by-case basis. Beyond that, fit depends on the complexity of the trust and the overall relationship, so reach out and we can talk it through.
More for trustees
Guides for trustees
Let’s talk about the trust you’re responsible for.
A private conversation about the trust, its beneficiaries, and whether our approach fits. Bring the trust document if you have it.
Disclosures
Reese Legacy Capital is a registered investment adviser in the Commonwealth of Pennsylvania. Registration does not imply a certain level of skill or training.
This page is general information about the firm’s services. It is not personalized investment, tax, or legal advice, or an offer to buy or sell any security. Reese Legacy Capital does not serve as trustee and does not provide legal or tax advice. Trustees remain responsible for their fiduciary duties and should rely on trust counsel for legal questions. Advisory services are provided only under a written advisory agreement.
Investing involves risk, including possible loss of principal. Options can expire worthless, cap upside, and still leave the account exposed to declines in the underlying securities. Past performance is not indicative of future results.
Assets are custodied at Charles Schwab & Co., Inc., or another qualified custodian, in the trust’s name. Schwab does not sponsor, supervise, or endorse Reese Legacy Capital.
Reese Legacy Capital is not affiliated with, sponsored by, or endorsed by The Hershey Company.
For a full description of services, fees, conflicts, and risks, request Form ADV Part 2A, or review the firm at adviserinfo.sec.gov. Those documents control if anything on this page is incomplete.